The 2024 ranking of the main French carriers is no longer just a list of revenue figures. European regulatory pressure on CO₂ emissions from heavy goods vehicles, combined with French tax incentives for greening fleets, is reshaping hierarchies. Groups that invest in technology gain a structural advantage over those that merely renew their fleets in kind.
CO₂ Regulation for Heavy Goods Vehicles 2024 and Its Impact on Carriers’ Strategies
The revised European regulation on CO₂ emissions standards for heavy vehicles, which came into effect on July 1, 2024, sets a trajectory for each manufacturer compared to 2019: -15% by 2025-2029, -45% in 2030-2034, -65% in 2035-2039, and -90% from 2040. New urban buses must be 90% zero-emission by 2030, and 100% by 2035.
For the carriers in the ranking, this constraint changes the game regarding fleet renewal. A group operating several thousand tractors can no longer spread its investments over ten years without risking ending up with depreciated assets, the infamous “stranded assets.” We observe that the top-ranked are already anticipating the 2030 milestone by integrating electric or natural gas vehicles into their regular routes.
Among the top 100 French carriers, those with internal research departments or partnerships with manufacturers benefit from priority access to the first series of electric tractors. Others face delivery delays that hinder their compliance.
Tax Super-Amortization and Fleet Greening in France
The French super-amortization scheme allows transport companies to deduct an additional fraction of the acquisition cost of heavy vehicles powered by electricity, hydrogen, or natural gas. This lever directly modifies the calculation of TCO (total cost of ownership) and makes certain alternative powertrains competitive against diesel over five to seven-year operating cycles.
Groups in the top 100 that structure their purchasing policy around this tax mechanism generate a measurable cash flow advantage from the first year. In contrast, mid-sized carriers, often positioned between the 50th and 100th places in the ranking, struggle to mobilize the necessary administrative resources to prepare the applications.
The ability to leverage tax incentives becomes a ranking factor as crucial as the volume of freight handled. A CFO who masters super-amortization and energy savings certificates (CEE) applied to transport weighs as much as an operations manager in the overall performance of the group.
Artificial Intelligence and Predictive Fleet Management
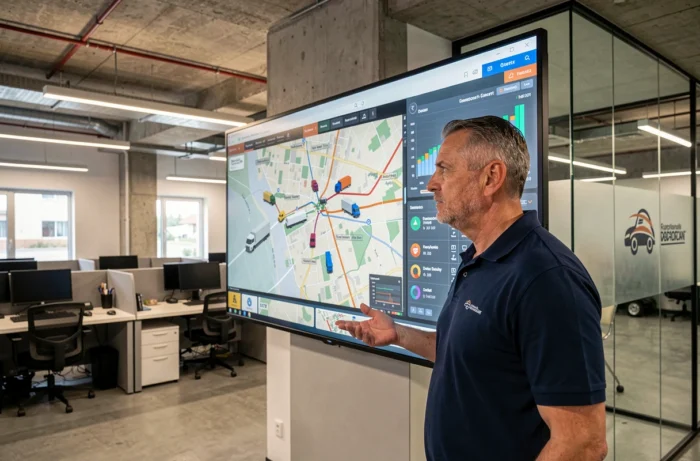
AI is no longer just marketing talk among major French carriers. According to L’Officiel des Transporteurs, fleet management is evolving towards predictive, proactive, and conversational management. Tools analyze fuel consumption, tire wear, and maintenance windows in real-time to optimize vehicle availability.
We see a clear difference between two categories of players:
- Groups that deploy AI across their entire operational chain (route planning, dynamic driver assignment, freight demand forecasting) and reap recurring productivity gains.
- Those that use AI only on isolated components (GPS optimization, maintenance alerts) without integration with their TMS (Transport Management System), limiting the benefits.
- Carriers that have not yet made the leap and outsource these functions via digital freight marketplaces, agreeing to share their margins with technology intermediaries.
However, the embedding of AI in operations remains without scale change for the majority of the sector. Only a handful of groups in the top 20 have industrialized these solutions to the point of making them a structural competitive advantage.
Digital Marketplaces and Access to Freight for Ranked Carriers
Marketplaces diversify access to freight and reshuffle the cards between historical carriers and more agile players. For a shipper, these platforms reduce dependence on a single provider. For a ranked carrier, they represent both an opportunity for filling capacity and a threat to margins.
The best-positioned groups technologically connect their TMS directly to the APIs of these platforms, allowing them to respond to spot tenders in a matter of minutes. This technical responsiveness becomes a selection criterion for large retail and automotive industry clients.
The interoperability of information systems now distinguishes carriers capable of capturing additional freight from those who remain confined to their historical contracts. A closed TMS, unable to communicate with market EDI or API standards, hinders growth more surely than an aging fleet.
Regional Eco-Contribution for Heavy Goods Vehicles and Its Consequences on the Ranking
The implementation of regional eco-contributions on heavy goods vehicles, for which the application decree was recently published, adds a layer of costs that varies by route. Carriers operating on regional routes subject to this tax must incorporate this additional cost into their pricing structures or absorb it into their margins.
For the top 100 players, geolocation and route calculation technology becomes a tool for fiscal as well as logistical management. Optimizing a route now involves balancing tolls, eco-contributions, and fuel consumption within the same algorithm.
Carriers that have not automated this calculation lose competitiveness with every tender, as they cannot offer precise pricing that reflects the reality of their operating costs by route. The 2024 ranking reflects this divide: the best-equipped groups technologically advance, while those still operating with spreadsheets lose ground.